Managing money effectively requires more than simply saving a portion of each paycheck or choosing a few investments. Strong finance and investment planning starts with understanding income, expenses, savings, debt and financial goals. Once that foundation is established, investing can become a powerful tool for pursuing long-term growth and building financial security.
Personal finance and investing are closely connected. A person who invests without an emergency fund or a plan for managing debt may be exposed to unnecessary financial pressure. At the same time, keeping all long-term savings in cash may make it harder to preserve purchasing power and build wealth over time. A balanced financial strategy considers both immediate needs and future objectives.
This complete guide explains how personal finance, budgeting, financial planning, investing, retirement preparation, portfolio diversification, risk management and wealth management fit together. It is designed to help readers understand the financial journey from establishing a strong foundation to developing long-term investment strategies.
What Is Finance and Investment?
Finance and investment refers to the broader process of managing money and allocating financial resources toward current needs and future goals. Personal finance covers areas such as earning, spending, budgeting, saving, borrowing and protecting money. Investing involves putting money into assets with the expectation of generating potential income or growth over time.
The two concepts should not be treated as separate subjects. Financial planning establishes how money should be managed, while investment planning determines how some of that money may be allocated for longer-term objectives.
A practical financial journey can be viewed as:
Assess → Budget → Save → Protect → Manage Debt → Set Goals → Invest → Diversify → Review → Build Wealth
For example, someone saving for an emergency expense may prioritize accessibility and stability, while someone saving for retirement decades in the future may have a greater ability to tolerate short-term investment fluctuations.
Investor.gov emphasizes defining financial goals, creating a savings and investment plan, understanding risk and researching investments as important parts of becoming an informed investor.
Understanding Personal Finance
Personal finance is the foundation of effective investment planning. It encompasses the decisions individuals and households make about income, spending, saving, debt, insurance, taxes and investments.
A strong personal finance strategy begins with understanding cash flow. Knowing how much money comes in each month and how much goes toward housing, food, transportation, debt, entertainment and other expenses helps determine how much can realistically be saved or invested.
Personal finance also involves preparing for unexpected circumstances. An emergency fund, appropriate insurance and responsible debt management can provide financial stability when circumstances change.
Investing should therefore be viewed as one part of a broader financial plan rather than the entire plan.
Why Personal Finance Comes Before Investing
Investing money that may be needed for an emergency can create problems if the investment loses value at the exact time the money is required. Similarly, investing aggressively while carrying expensive debt may not always be the most effective approach.
A stronger strategy begins by understanding the current financial position and addressing fundamental financial needs. Once those areas are under control, long-term investing can be incorporated into the plan.
Assessing Your Current Financial Situation
Before setting investment targets, it helps to understand where the finances currently stand. Two useful measures are net worth and cash flow.
Net worth is calculated by subtracting liabilities from assets:
Assets − Liabilities = Net Worth
Assets can include savings, investments, retirement accounts, real estate and other valuable property. Liabilities may include credit cards, mortgages, student loans, auto loans and other outstanding debt.
Net worth provides a starting point for measuring financial progress. It can increase through higher savings, investment growth, debt reduction or a combination of these factors.
Monthly cash flow provides another important perspective. Subtracting monthly expenses from income shows how much money remains for savings, debt repayment and investments. If spending regularly exceeds income, the first priority may be improving cash flow rather than increasing investment contributions.
A financial review can also examine whether emergency savings are adequate, whether high-interest debt is being addressed, whether retirement contributions are on track and whether existing investments are properly diversified.
Budgeting and Saving
Budgeting connects everyday financial decisions with long-term objectives. A budget is not necessarily about restricting every discretionary purchase. Instead, it provides a framework for deciding where income should go.
A useful budget starts with income and essential expenses. Discretionary spending is then considered alongside savings and debt obligations. Reviewing actual spending over several months can reveal recurring costs that may otherwise go unnoticed.
Different approaches can be effective depending on individual preferences. Some people use percentage-based budgets, while others prefer zero-based budgeting or a pay-yourself-first strategy. The most effective method is generally the one that can be followed consistently.
Saving should also become part of the financial system rather than something that happens only when money is left over. Automated transfers can make saving more consistent and reduce the temptation to spend money that was intended for future goals.
Practical Ways to Improve Saving
Some straightforward approaches include:
- Automating transfers immediately after receiving income.
- Reviewing recurring subscriptions and unnecessary expenses.
- Increasing savings when income increases.
- Separating short-term savings from long-term investments.
- Setting specific savings targets instead of relying on vague intentions.
Over time, consistent saving creates the capital needed for emergency reserves, major purchases and long-term investing.
Setting Financial Goals
Financial goals provide direction for both saving and investing. Without a clear objective, it can be difficult to determine how much money is needed, how long it should remain invested or how much risk is appropriate.
Short-term goals may involve emergency savings, debt repayment or upcoming purchases. Medium-term goals can include buying a home, paying for education or starting a business. Long-term goals often include retirement, financial independence and wealth transfer.
The time horizon of each goal matters because investment choices should generally reflect when the money will be needed.
Examples of Financial Goals
- Short term: Build an emergency fund or pay off expensive debt.
- Medium term: Save for a home, vehicle or education.
- Long term: Build retirement savings or achieve financial independence.
Financial goals are more useful when they are measurable. Instead of simply deciding to save more, a specific target can establish the amount to save and the timeframe for reaching it.
Investor.gov recommends establishing specific financial goals and considering the time available to reach those goals when developing an investment plan.
Building an Emergency Fund
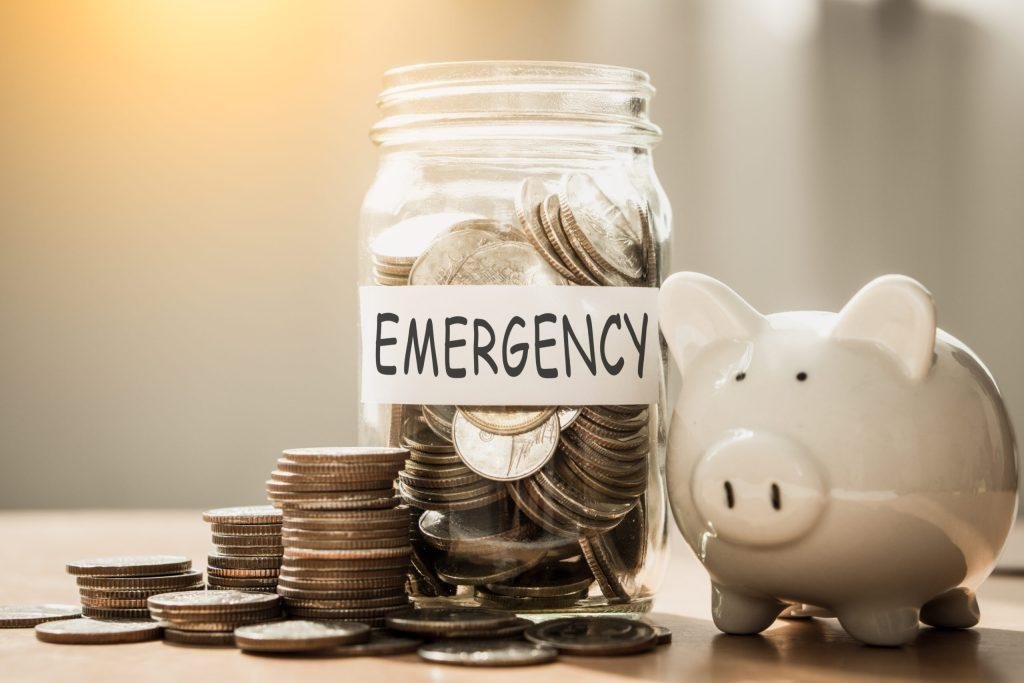
An emergency fund provides accessible savings for unexpected expenses. These may include medical bills, vehicle repairs, home repairs, temporary income disruption or other costs that are difficult to predict.
The appropriate size of an emergency fund depends on personal circumstances. Income stability, monthly expenses, dependents, debt obligations and insurance coverage can all affect the amount that may be appropriate.
An emergency fund should generally prioritize accessibility and stability rather than maximizing investment returns. The purpose is to provide financial protection when money is needed unexpectedly.
The Consumer Financial Protection Bureau recommends establishing a dedicated emergency savings fund for unplanned expenses and notes that even relatively small savings can provide financial protection.
Emergency Fund vs. Investment Portfolio
| Emergency Fund | Investment Portfolio |
| Designed for unexpected expenses | Designed primarily for longer-term goals |
| Prioritizes accessibility | Can prioritize growth |
| Generally focuses on stability | Can experience significant volatility |
| May be needed at short notice | Often has a longer investment horizon |
Keeping these purposes separate can help prevent an investor from having to sell long-term investments during an unfavorable market period to cover an unexpected expense.
Managing Debt Before Investing
Debt management is another important component of financial planning. Not all debt has the same impact, but high-interest debt can make it difficult to build wealth because a significant portion of available income may be directed toward interest payments.
Two common debt repayment approaches are the debt avalanche and debt snowball methods. The avalanche approach generally prioritizes the highest-interest debt, while the snowball approach focuses on the smallest balance first.
The avalanche method can reduce interest costs more efficiently, while the snowball approach can provide psychological motivation by creating quicker milestones.
Questions to Consider Before Investing While Carrying Debt
- What is the interest rate on the debt?
- Is there an employer retirement contribution or matching benefit?
- Is there an emergency fund?
- Can monthly cash flow support both debt repayment and investing?
- What are the investment time horizon and risk level?
Investor.gov includes paying off high-interest debt as an important consideration for investors preparing to invest.
Understanding Different Investment Options
Once the financial foundation is established, investors can begin exploring different investment options. Each investment type has its own potential benefits, risks, costs and role within a financial plan.
Common options include stocks, bonds, mutual funds, ETFs, real estate and cash-oriented investments.
Stocks
Stocks represent ownership in a company. Investors may benefit from increases in share prices and, in some cases, dividends.
Stocks can provide substantial long-term growth potential, but they can also experience significant price fluctuations. Individual companies may face business, financial or industry-specific challenges that cause their share prices to decline.
Bonds
Bonds generally represent debt issued by governments, municipalities or companies. Investors may receive interest payments and repayment of principal according to the terms of the bond.
Bonds can provide income and diversification, but they still carry risks. Interest-rate changes can affect bond prices, while credit risk can arise if an issuer experiences financial difficulties.
Mutual Funds
Mutual funds pool money from multiple investors and invest that money according to a defined strategy. A mutual fund may invest in stocks, bonds or other assets.
Funds can provide diversification without requiring an investor to purchase every individual security separately. However, investors should understand the fund’s objectives, holdings, fees and risks.
Exchange-Traded Funds
ETFs are pooled investment vehicles that trade on exchanges. Like mutual funds, they can provide exposure to a broad collection of investments.
ETFs may track market indexes, sectors, geographic markets, bonds or other assets. Investors should evaluate the underlying holdings and costs rather than choosing a fund solely because of its recent performance.
Real Estate
Real estate can be used as part of a broader wealth-building strategy, although direct property ownership can involve substantial costs, maintenance, financing requirements and limited liquidity.
Investor.gov provides educational information about stocks, bonds, mutual funds, ETFs and other investment products and emphasizes the importance of understanding their risks and costs.
Investing for Beginners
Investing for beginners becomes easier when the process starts with a financial goal rather than a particular investment product.
Someone investing for retirement may have a very different strategy from someone saving for a purchase within two years. The first investor may have more time to tolerate market volatility, while the second may need greater emphasis on preserving the money needed for the near-term goal.
A beginner should first determine how much money can reasonably be invested without compromising essential expenses and financial reserves. Risk tolerance and risk capacity should then be considered.
A Simple Beginner Investing Process
- Define the financial goal. Understand why the money is being invested.
- Determine the time horizon. Identify when the money may be needed.
- Assess risk. Consider how much volatility can be tolerated and financially absorbed.
- Choose an appropriate account. Account type can affect taxes, access and investment options.
- Research diversified investments. Understand the underlying assets, fees and risks.
- Invest consistently. Regular contributions can support disciplined investing.
- Review periodically. Adjust the strategy when goals or circumstances change.
This process helps beginners avoid selecting investments based solely on popularity, recent returns or social-media recommendations.
Stocks and Bonds
Stocks and bonds can serve different purposes within a portfolio. Stocks generally provide greater potential for long-term capital growth but can experience greater volatility. Bonds can provide income and diversification but are affected by interest rates, credit conditions and inflation.
| Factor | Stocks | Bonds |
| Represents | Ownership | Debt |
| Potential growth | Generally higher | Generally lower than stocks |
| Volatility | Can be high | Varies by bond type |
| Potential income | Dividends | Interest |
| Key risks | Market and business risk | Interest-rate and credit risk |
| Typical role | Long-term growth | Income and diversification |
There is no universally correct stock-to-bond ratio. Asset allocation should reflect the investor’s goals, time horizon and ability to withstand losses.
Mutual Funds and ETFs
Mutual funds and ETFs allow investors to gain exposure to multiple investments through a single fund. This can simplify diversification and provide access to professionally managed or index-based portfolios.
The primary structural difference is how the investments are traded. Mutual funds are generally bought and sold based on their calculated net asset value, while ETFs trade throughout the market day.
Investors comparing these products should examine more than recent performance. The expense ratio, underlying holdings, investment objective, diversification, liquidity and tax considerations can all affect suitability.
What Is an Index Fund?
An index fund is designed to track a specific market index. Rather than attempting to select securities that will outperform the market, an index strategy generally seeks to replicate the performance of its chosen benchmark, before fees and other costs.
Index funds can offer broad market exposure, but they still carry market risk and should be evaluated based on their specific objectives and costs.
Retirement Planning
Retirement planning is one of the most important applications of long-term financial planning. It involves estimating future expenses, determining how much needs to be saved and deciding how investments can support those future needs.
Retirement planning should consider current spending, expected retirement expenses, desired retirement age, existing assets, potential income sources, inflation, taxes and healthcare costs.
Starting earlier can provide more time for contributions and potential compound growth. It also provides more opportunities to adjust the plan when circumstances change.
For U.S. investors, retirement planning may involve accounts such as 401(k) plans, traditional IRAs and Roth IRAs. These accounts have different tax treatments and eligibility rules, so current IRS guidance should be consulted before making decisions.
Retirement Planning Considerations
A retirement plan should consider:
- Expected retirement age
- Current and future spending
- Savings rate
- Existing retirement assets
- Expected income sources
- Inflation
- Healthcare expenses
- Investment risk
- Tax considerations
- Expected retirement duration
Portfolio Diversification and Asset Allocation
Portfolio diversification means spreading investments across different securities, industries, asset classes or geographic markets. Its purpose is to reduce concentration risk.
For example, an investor whose portfolio consists almost entirely of one company faces substantial risk if that company experiences a major decline. Spreading investments across multiple holdings can reduce the impact of any single investment.
Diversification does not eliminate losses. A diversified portfolio can still decline when broader markets fall. Instead, diversification aims to reduce the impact of a single security, sector or asset class performing poorly.
Asset allocation is related but different. It describes how a portfolio is divided among asset categories such as stocks, bonds and cash.
Ways to Diversify a Portfolio
Diversification can involve:
- Different asset classes
- Different industries
- Different companies
- Different geographic regions
- Different market segments
- Different bond issuers and maturities
Investor.gov explains that diversification can reduce investment risk by spreading money among different investments.
Risk Management in Investing
Risk management involves identifying the risks that could interfere with financial goals and taking reasonable steps to manage them.
Market risk is the possibility that investments will decline in value. Inflation risk concerns the loss of purchasing power over time. Liquidity risk occurs when an investment may be difficult to sell quickly. Credit risk is particularly relevant to bonds and other debt investments.
Concentration risk is another major concern. A portfolio heavily dependent on one company, sector or asset class can experience disproportionate losses when that area performs poorly.
Behavioral risk is often overlooked. Investors can make decisions based on fear, FOMO, overconfidence or short-term market news. A written investment plan can help reduce emotional decision-making.
Risk Tolerance vs. Risk Capacity
Risk tolerance refers to how comfortable someone is with investment volatility. Risk capacity refers to how much financial loss that person can actually afford.
These are not always the same. An investor may feel comfortable with significant market fluctuations but still need to protect money that will be required for an important near-term financial goal.
Tax-Efficient Investing
Taxes can influence the amount of investment return that ultimately remains available to an investor. The tax treatment can vary depending on the type of investment, account, holding period, income level and applicable tax laws.
For U.S. investors, tax-advantaged accounts such as 401(k) plans, traditional IRAs and Roth IRAs can have different rules regarding contributions and withdrawals. Other accounts, such as HSAs, can also have specific tax advantages when eligibility requirements are met.
Tax-efficient investing may involve understanding capital gains, dividends, interest income, tax-advantaged accounts and the placement of different investments within taxable and tax-advantaged accounts.
Because tax rules change, investors should verify current requirements through authoritative government sources or consult a qualified tax professional when appropriate.
Long-Term Investment Strategies
Long-term investment strategies generally emphasize consistency, diversification and alignment with financial goals rather than frequent attempts to predict short-term market movements.
Buy-and-hold investing involves maintaining investments over an extended period. Passive investing generally seeks to track a market index rather than frequently trade securities. Dollar-cost averaging involves investing at regular intervals instead of attempting to identify the perfect market entry point.
Goal-based investing takes a more personalized approach by connecting each investment decision with a specific financial objective.
Common Long-Term Approaches
- Buy and hold: Maintain investments over a long period.
- Passive investing: Track a market index or defined benchmark.
- Dollar-cost averaging: Invest predetermined amounts at regular intervals.
- Goal-based investing: Align investment decisions with specific financial objectives.
- Diversified investing: Spread exposure across different investments and asset classes.
No strategy guarantees a positive return. The most appropriate approach depends on the investor’s circumstances and financial objectives.
Wealth-Building Strategies
Building wealth is usually a long-term process involving income, spending, saving, investing and risk management.
Increasing income can create more capital for financial goals, but managing expenses is equally important. The amount left after essential and discretionary spending represents potential capital for savings, debt repayment and investments.
Investment costs also matter. Even relatively small fees can reduce the amount of money that remains invested and compounds over many years. Investors should therefore understand expense ratios, account fees, trading costs and other charges associated with their investments.
Wealth management also involves protecting assets after they have been accumulated. Insurance, estate planning, beneficiary designations, tax planning and diversification can become increasingly important as financial circumstances become more complex.
Core Wealth-Building Principles
- Increase sustainable income.
- Maintain reasonable spending.
- Save consistently.
- Invest for appropriate long-term goals.
- Diversify investments.
- Control unnecessary fees.
- Manage taxes.
- Protect accumulated assets.
- Review the financial plan regularly.
Choosing Financial Products or Professional Advice
Financial products should be evaluated based on their purpose rather than marketing claims. Before selecting an investment, investors should understand its potential return, risk, fees, liquidity, tax treatment and underlying assets.
It is also important to understand who provides the product and how they are compensated. Conflicts of interest can influence recommendations, so transparency is valuable when evaluating financial services.
Common Investment Mistakes
Even a well-designed financial plan can be undermined by avoidable investment mistakes. Many problems occur when investors focus too heavily on short-term performance instead of long-term objectives.
One common mistake is investing without a specific goal. Another is taking excessive risk because an investment has recently performed well. Investors can also hurt long-term results by panic selling during market declines or constantly changing strategies based on short-term news.
A Simple Finance and Investment Plan for Beginners
A beginner can approach financial planning as a series of connected decisions rather than trying to solve everything at once.
First, calculate net worth and understand monthly cash flow. This establishes the financial starting point. Next, create a sustainable budget and build appropriate emergency savings. High-interest debt should also be evaluated.
Once the financial foundation is stronger, define short-, medium- and long-term financial goals. Each goal can then be assigned a timeframe and an appropriate savings or investment strategy.
For long-term goals, investors can research diversified investments, select an appropriate account and establish a consistent contribution strategy. The portfolio can then be reviewed periodically to ensure it remains aligned with the original objective.
The Basic Financial Roadmap
- Assess: Understand income, expenses, assets and debt.
- Budget: Create a sustainable spending and saving system.
- Protect: Establish emergency savings and appropriate financial protection.
- Manage debt: Prioritize expensive debt.
- Set goals: Define measurable financial objectives.
- Invest: Choose investments appropriate to the goals.
- Diversify: Reduce unnecessary concentration risk.
- Review: Reassess the plan as circumstances change.
Reviewing and Updating a Financial Plan
A financial plan should evolve as circumstances change. Income, expenses, family responsibilities, investment objectives and retirement expectations can all change over time.
A monthly review can focus on spending, savings and debt. A more detailed annual review can examine net worth, investment allocation, retirement contributions, insurance, taxes and financial goals.
Major life events may also justify a financial review. Marriage, divorce, having children, changing careers, purchasing a home, receiving an inheritance, starting a business or approaching retirement can all affect the financial plan.
Portfolio rebalancing may also be appropriate when the investment allocation moves significantly away from its intended structure. The purpose of reviewing a portfolio is not to make constant changes but to ensure that the strategy continues to support the financial goals.
Finance and Investment Glossary
Asset Allocation: The process of dividing an investment portfolio among asset classes such as stocks, bonds and cash.
Bonds: Debt investments issued by governments, municipalities or companies.
Capital Gains: The increase in value realized when an investment is sold for more than its purchase price.
Compound Growth: Growth that occurs when returns generate additional returns over time.
Diversification: Spreading investments across different securities or asset classes to reduce concentration risk.
ETF: An exchange-traded fund that holds a collection of investments and trades on an exchange.
Expense Ratio: A measure of the annual operating expenses charged by an investment fund.
Financial Planning: The process of organizing financial resources around current needs and future goals.
Inflation: A general increase in prices that reduces the purchasing power of money.
Mutual Fund: A pooled investment vehicle that collects money from investors and invests it according to a defined strategy.
Portfolio: The collection of investments owned by an individual or organization.
Risk Tolerance: An investor’s willingness to accept investment fluctuations or losses.
Time Horizon: The period during which money is expected to remain invested before it is needed.
Wealth Management: A broader approach to managing, growing and protecting financial assets.
Conclusion
Effective finance and investment management is not about finding one perfect stock, fund or financial product. It is about creating a financial system that connects present decisions with future objectives.
The process starts with personal finance. Understanding income and expenses, creating a budget, building emergency savings and managing debt can establish a stronger foundation. Financial goals then provide direction, while investment planning determines how available capital may support those goals over time.
Investors also need to understand risk, diversification, investment costs and tax considerations. Stocks, bonds, mutual funds and ETFs can all play different roles, but their suitability depends on the investor’s circumstances and objectives.
Long-term wealth growth is ultimately a process rather than a single decision. Consistent saving, disciplined investing, thoughtful risk management and regular financial reviews can help create a structured approach to pursuing financial security.
Frequently Asked Questions
Finance and investment involves managing money and allocating financial resources toward current needs and future goals. It includes personal finance activities such as budgeting, saving and debt management as well as investing in assets such as stocks, bonds, mutual funds and ETFs.
Saving generally focuses on preserving money and keeping it accessible for short-term needs and emergencies. Investing involves accepting a degree of risk in pursuit of potential long-term growth or income.
A beginner should first understand their financial position, establish appropriate emergency savings, consider high-interest debt and define financial goals. They can then determine the investment timeframe, assess risk and research diversified investment options.
There is no universal amount. The appropriate contribution depends on income, expenses, debt, emergency savings and financial goals. A sustainable amount that can be invested consistently is generally more useful than an amount that creates financial strain.